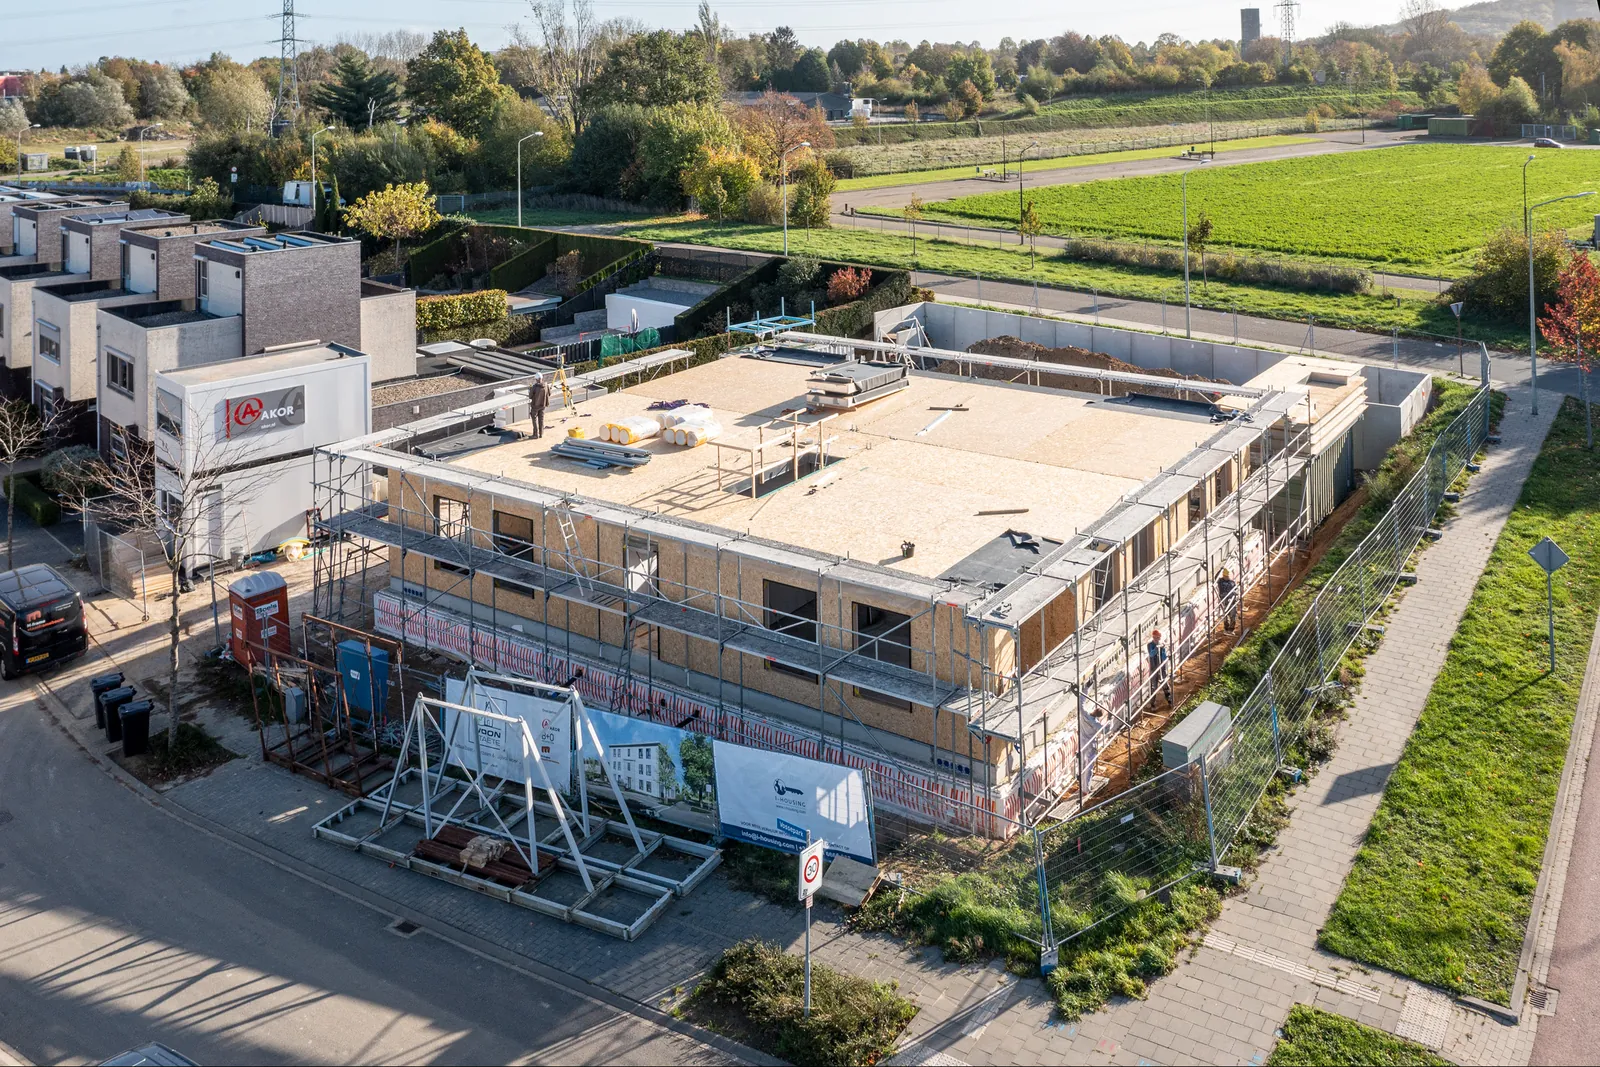
Invest while new homes are under construction
Opbouw is a loan with a term of twelve to eighteen months, starting once the planning permission is final. Interest is fixed at 8% a year and paid quarterly. Your loan is secured by a second mortgage on the land on which the homes will stand.
- Interest
- 8% a year, paid quarterly
- Term
- 12 to 18 months
- Security
- 2nd mortgage on the land
- Purpose
- Construction finance
- From
- € 200,000
Your collateral grows as the homes take shape
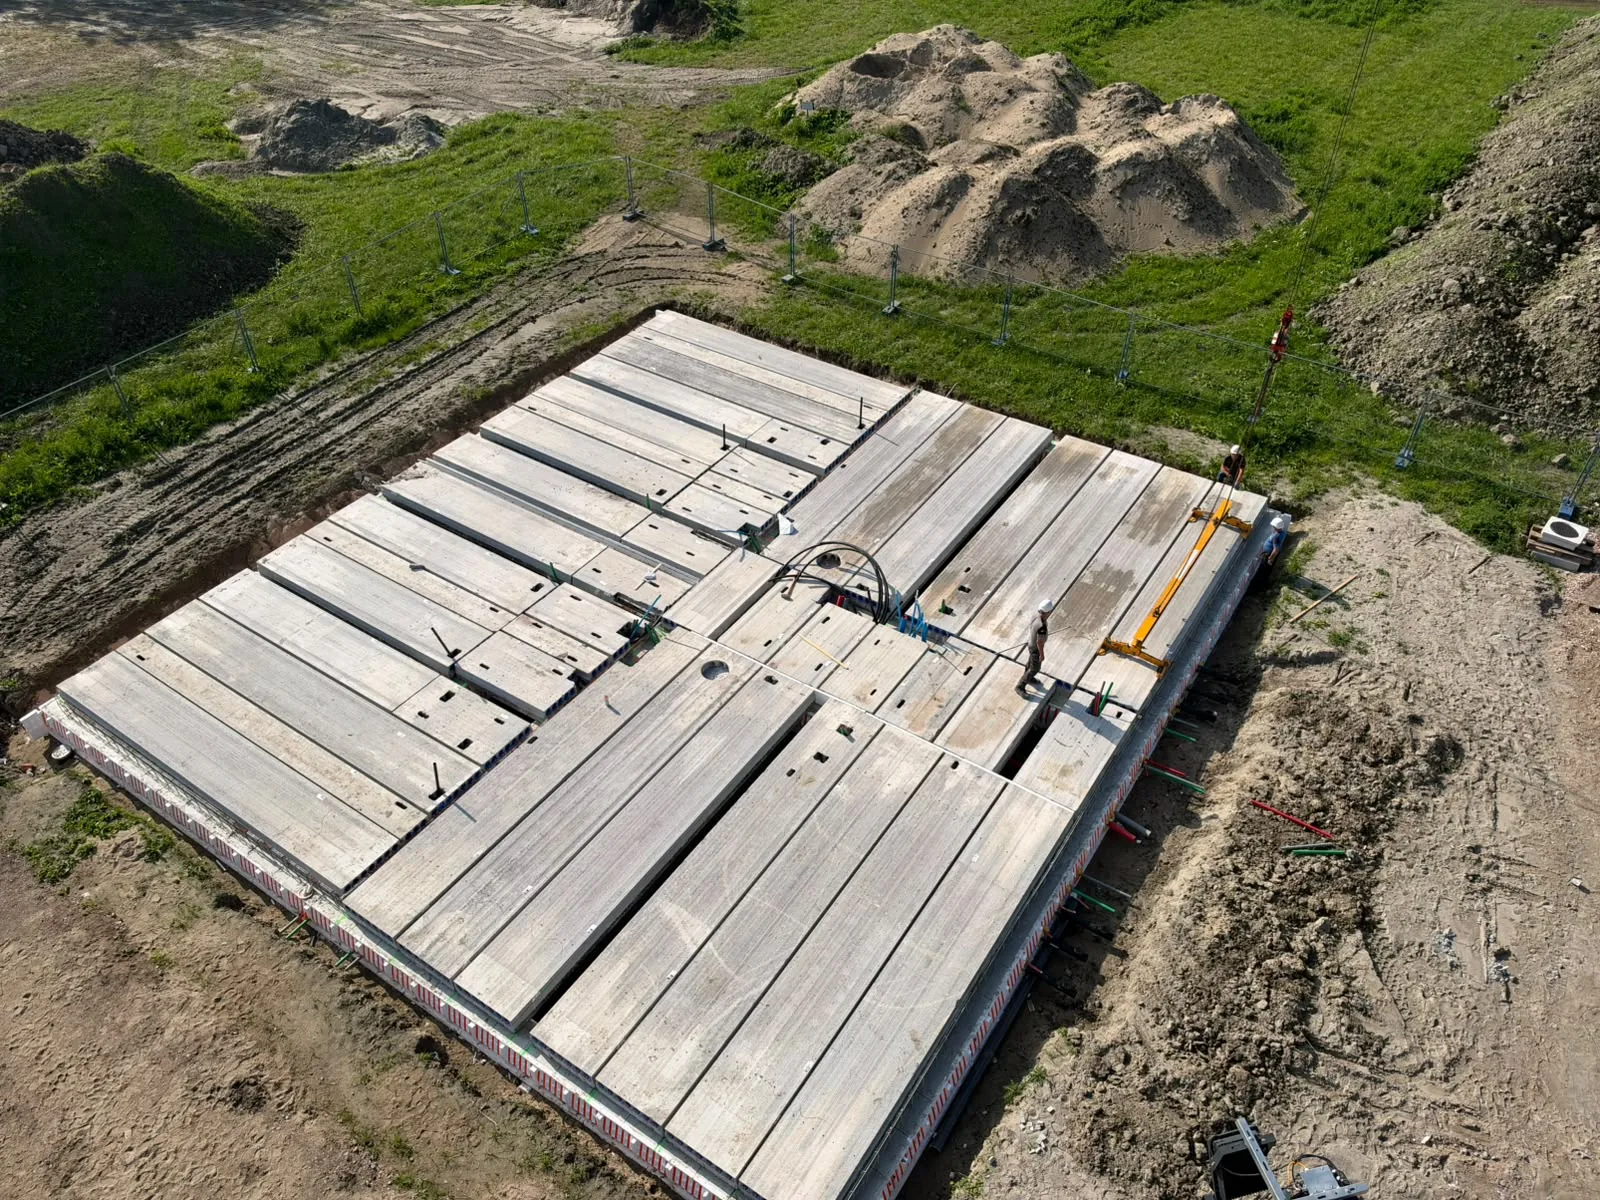
When the loan starts, your second mortgage covers the land. By then the land has been valued as a plot with permission for a set number of homes. During construction the land is divided into a separate unit for each home, so your collateral grows as the homes progress, until they are complete.
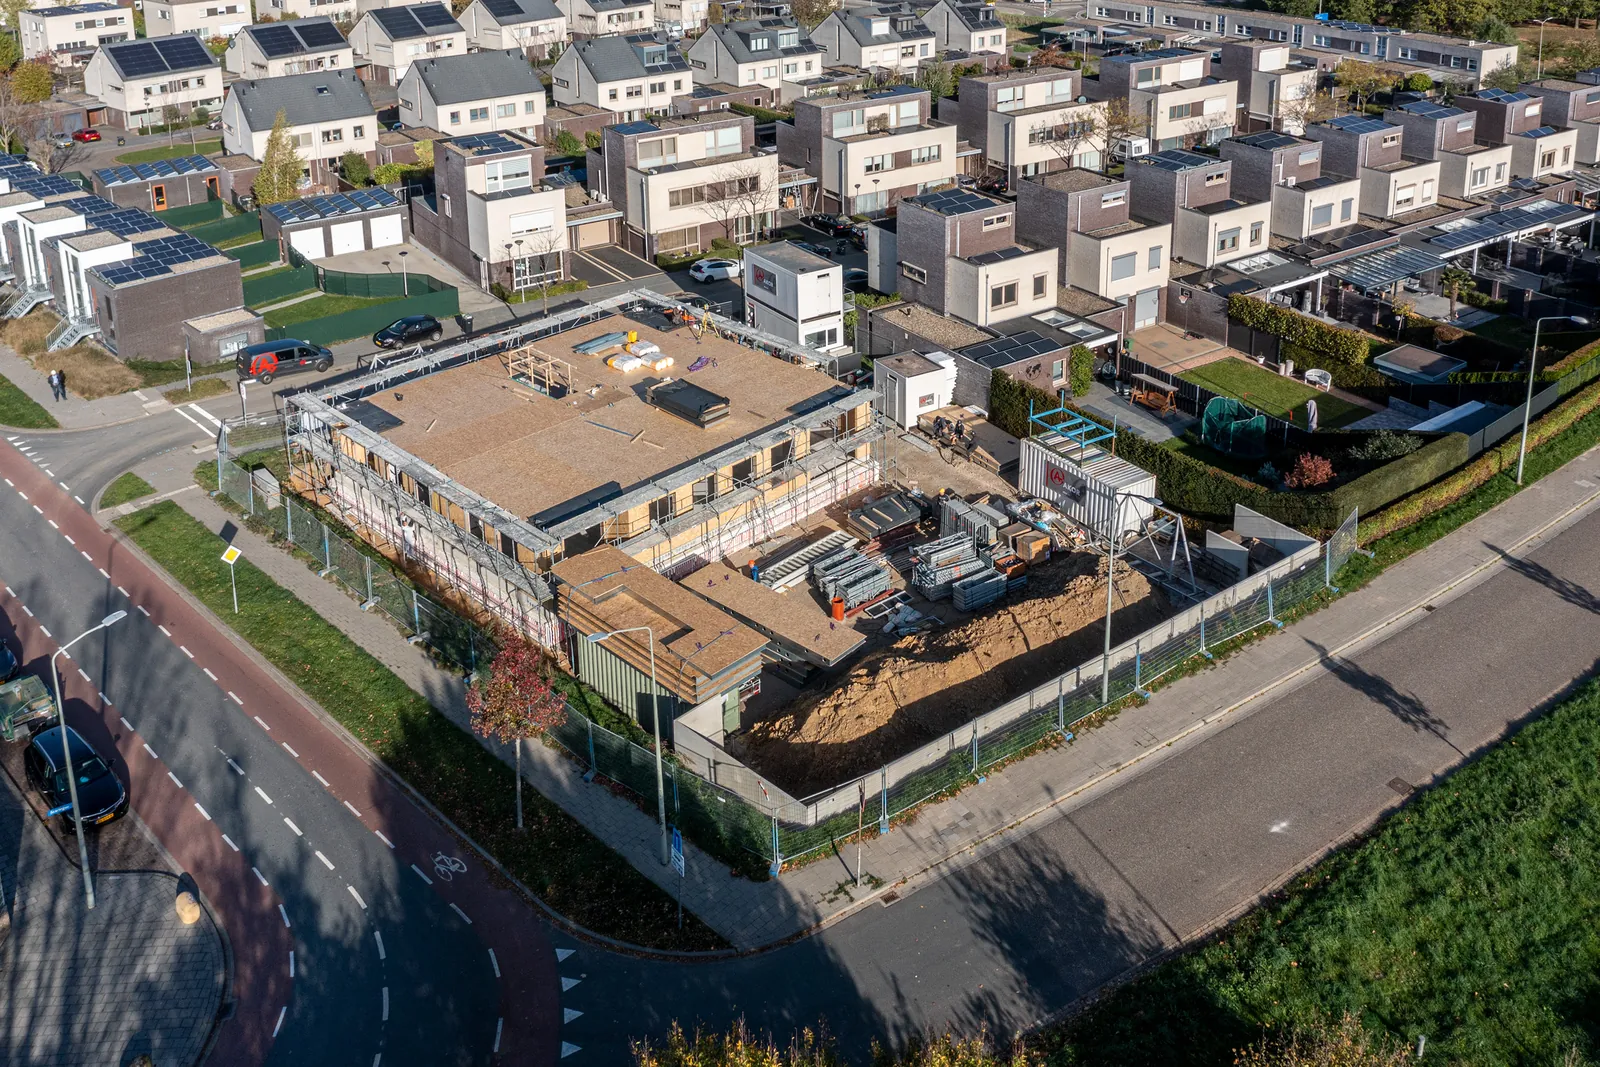
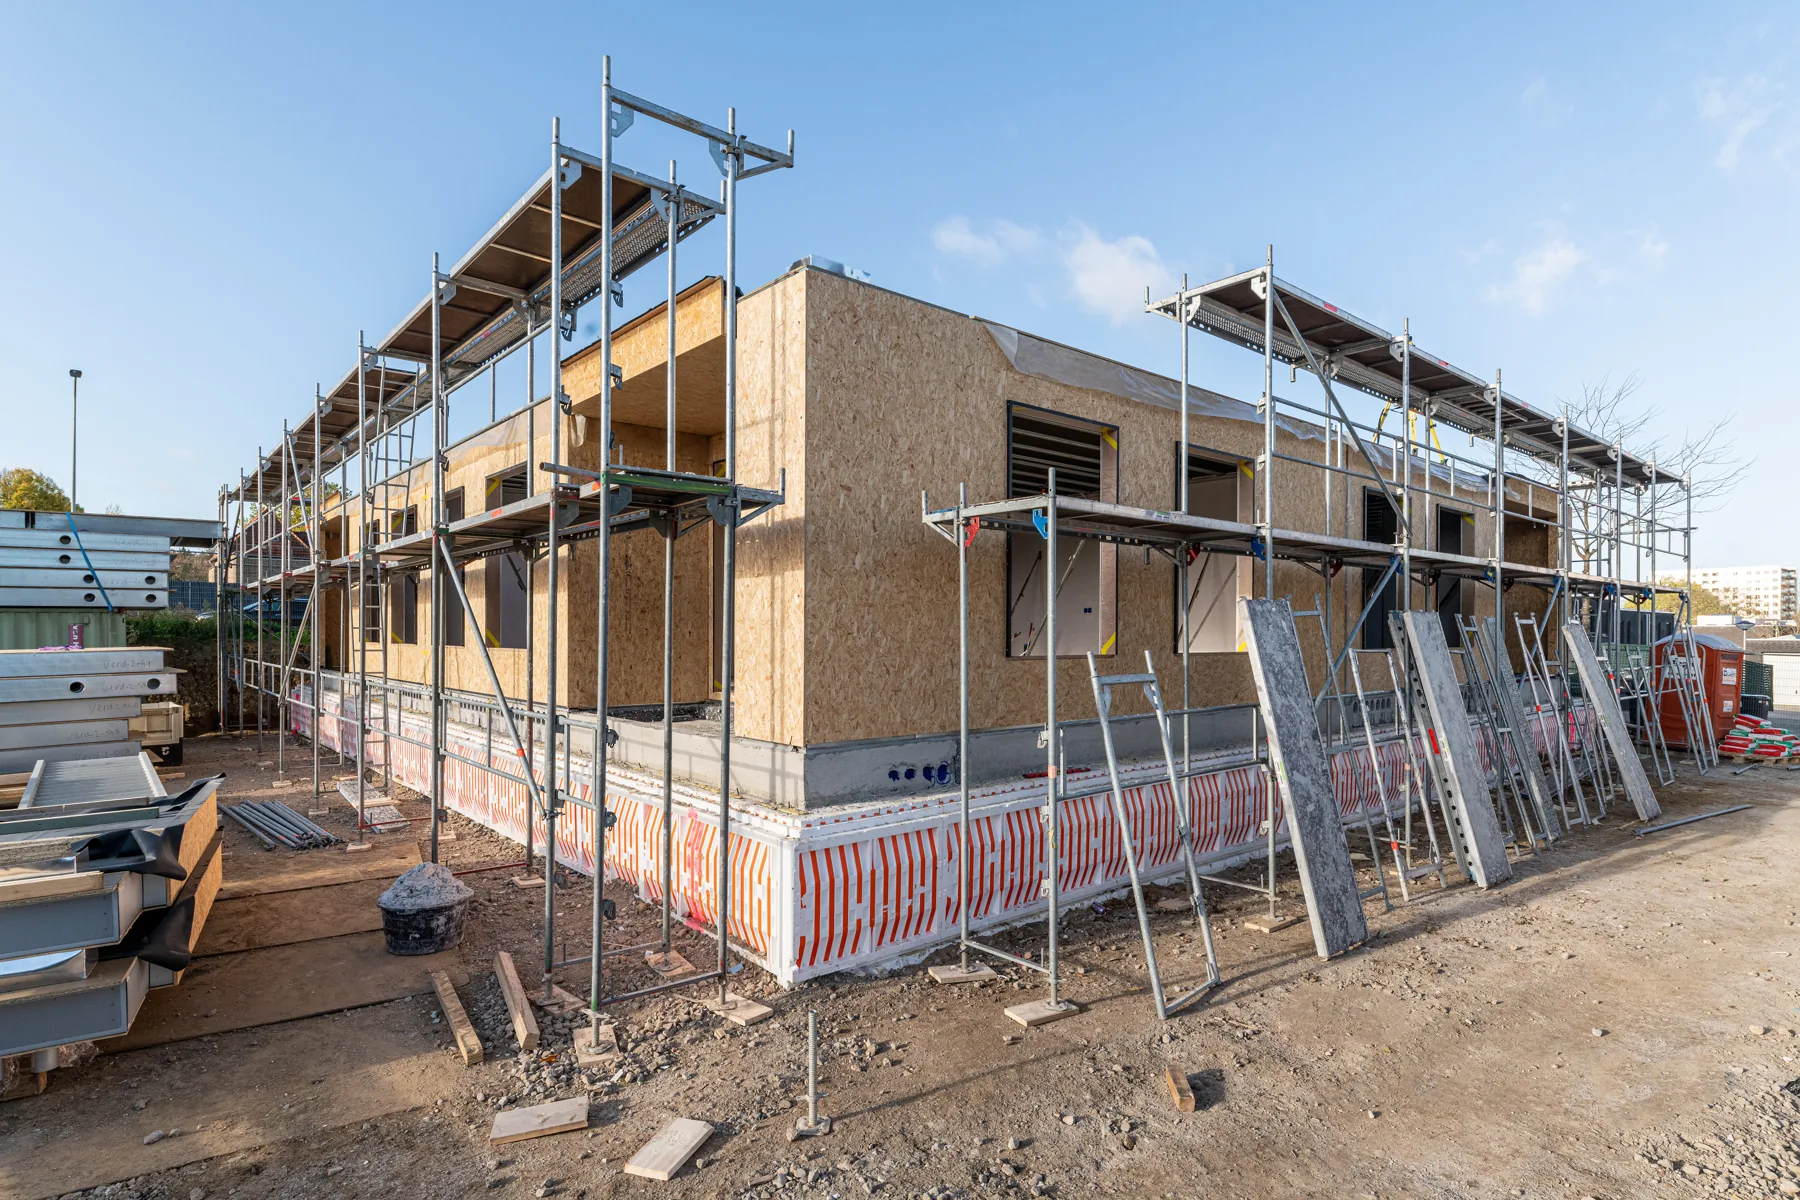
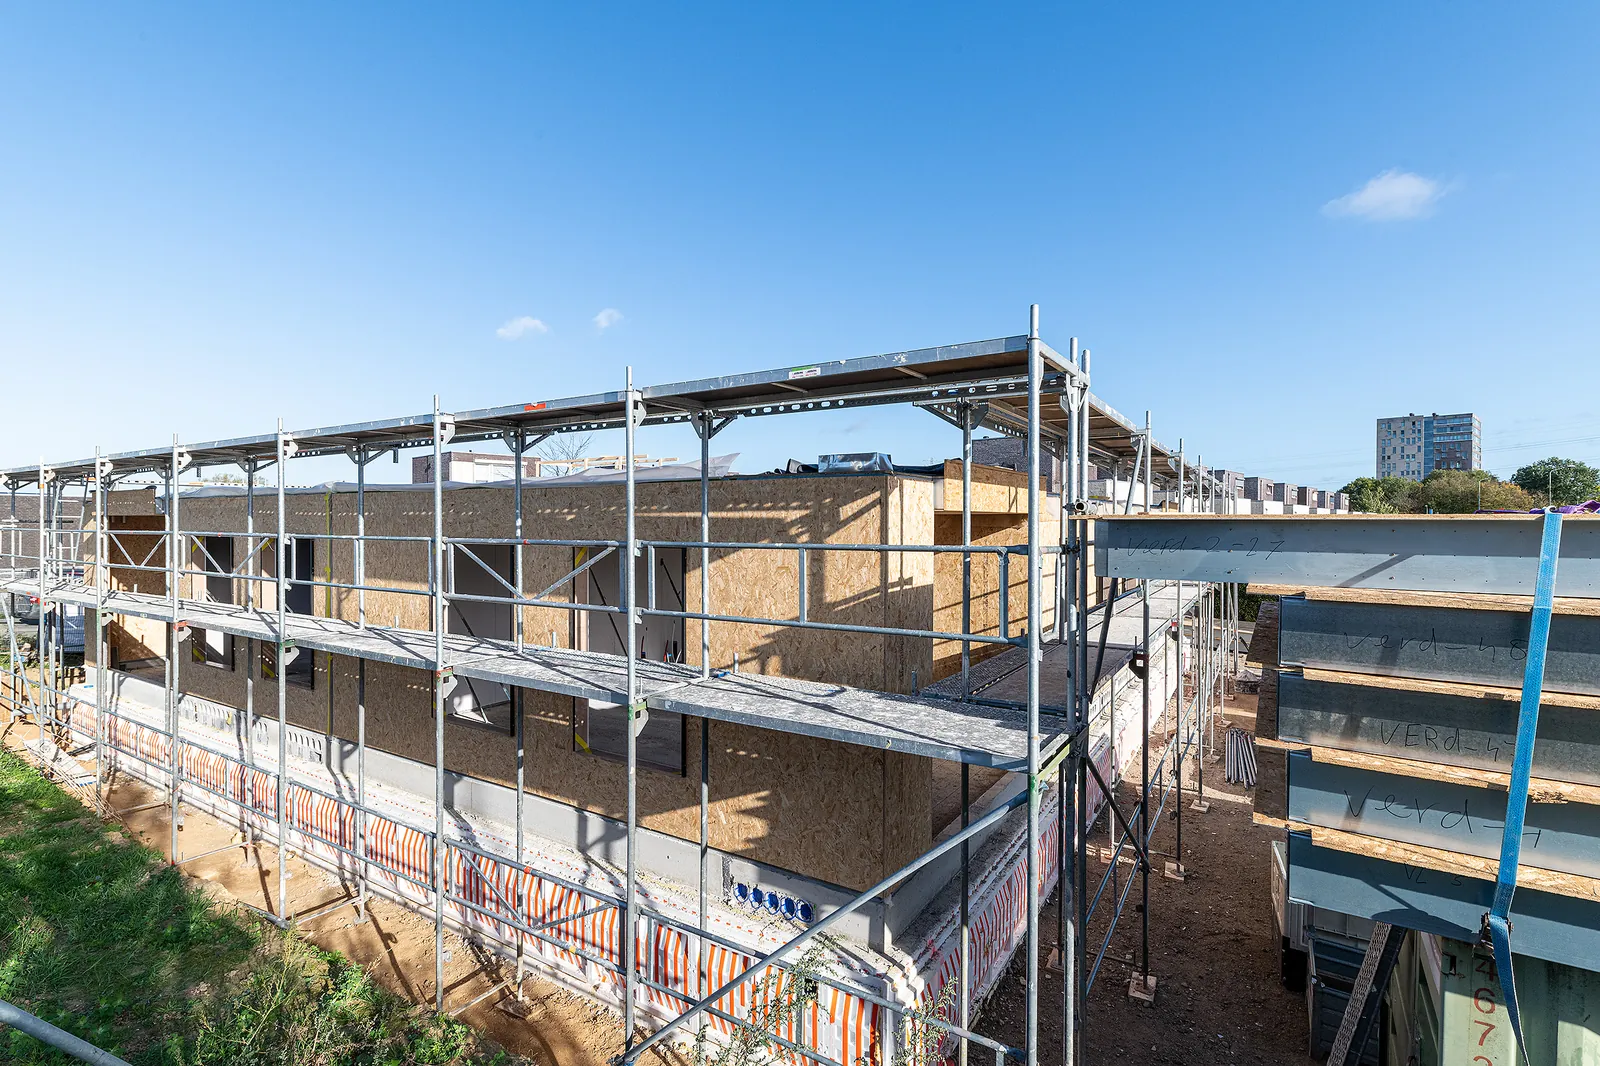
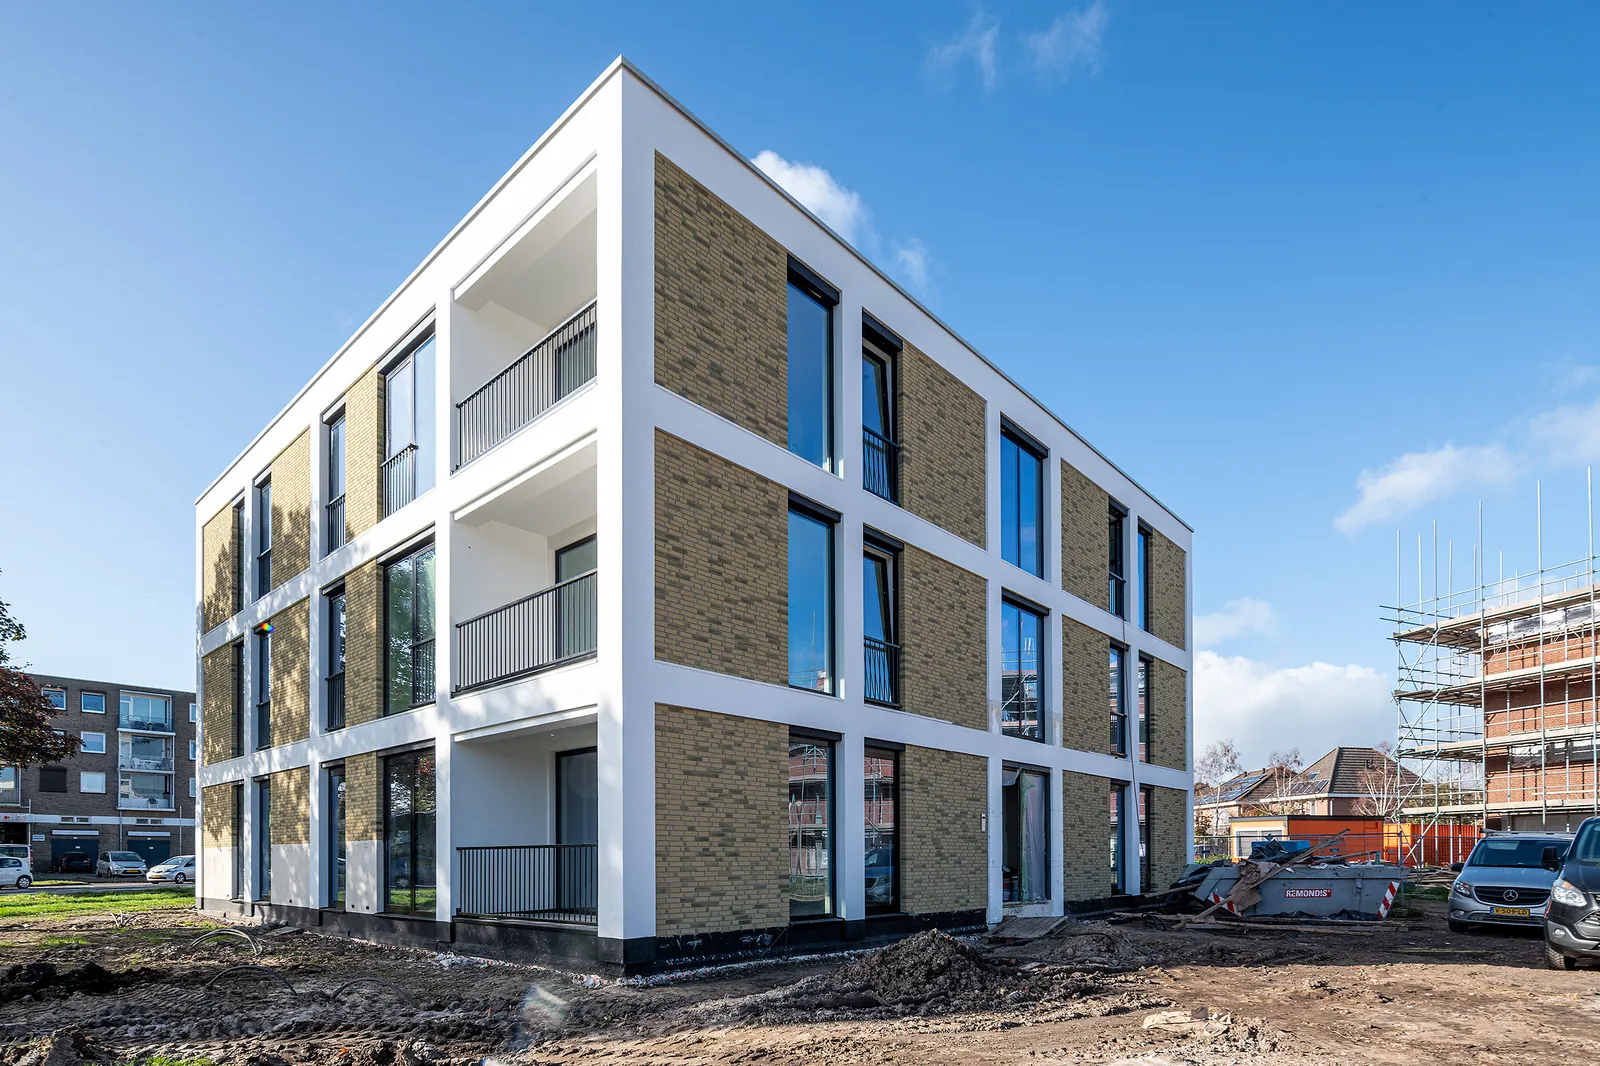
You provide your loan only once construction can begin
Together with the other lenders, you provide a loan to the company that owns the land and commissions the homes on it. Each project sits in its own company, which owns only that land and those homes. What happens in another project therefore does not affect your loan.
Before construction comes development: securing the site, agreeing the plan with the municipality and obtaining planning permission. That process takes three to five years on average, and Woonstaete Ontwikkeling funds it from its own equity. We raise the loan from investors only once the planning permission is final and construction can begin.
At that point no objection or appeal against the permission is still pending. The land can therefore be valued as a plot with permission for the approved homes. You can read the valuation report in the portal.
The notary creates a second mortgage on that land and registers it with the Land Registry (Kadaster). The first mortgage is held by the lender financing the construction.
An independently appointed foundation holds the second mortgage on behalf of all the lenders and represents their interests. As a result you have a single point of contact, and Woonstaete cannot replace the foundation without the lenders' consent.
Fixed quarterly interest, with the loan amount repaid at the end
Interest is 8% a year, fixed for the entire term and paid quarterly in arrears. We raise the full loan amount for the construction period in one go, so you commit your money once for the whole term.
- 8% interest a year, fixed for the entire term
- Paid quarterly, four to six times in all
- A second mortgage on the land, with security that increases during the construction period
- The plan, the planning permission and delivering the homes
- Letting the homes afterwards, so there is nothing for you to do
€ 4,000per quarter
This example is based on the fixed rate of 8% and is not a commitment. The term and the interest start date are set out in the project documents.
An Opbouw loan at a glance
The term and interest start date of your loan are set out in the project documents. The key terms include:
Three loans, each with its own profile
Rust and Stabiel are loans on tenanted homes, secured by a first or a second mortgage. Opbouw runs during the construction period, secured by a second mortgage on the land.
Rust
5% interest a yearOn tenanted homes, with a first mortgage. Interest paid monthly, term 5 to 7 years, from € 100,000.
Read about RustStabiel
6.25% interest a yearOn tenanted homes, with a second mortgage. Interest paid monthly, term 5 to 7 years, from € 100,000.
Read about StabielOpbouw
8% interest a yearDuring the construction period, with a second mortgage on the land. Interest paid quarterly, term 12 to 18 months, from € 200,000.
This pageThe offering shows which project your Opbouw loan belongs to.
View the offeringChoose your next step
We would be glad to meet you for a personal conversation. You can already create an account in the portal. Investing is not possible yet; as soon as a project opens, your account will be ready and you will find all the documents there.
Create an account
Investing is not possible yet. As soon as a project opens, you can read the documents in the investor portal and sign online. Once your identity has been verified, you will receive the payment request.
Go to the portal
A personal conversation
Vincent Sybrandy will take you through the loan, the security and the documents, with no obligation at all.
investeren@woonstaete.nl
+31 6 37 39 74 69
The brochure
Woonstaete's loans, the mortgage and the foundation, what we have delivered and how investing works.
Request the brochureRequest the brochure
Four questions we often hear about Opbouw
Why is the security on the land rather than the homes?
When the loan starts, the homes are not there yet. The notary therefore creates the second mortgage on the land, which has final planning permission. As construction progresses, the land is divided into a separate unit for each home and the homes come under the same mortgage, so your collateral grows with them.
What if the planning permission is not yet final?
Then we do not raise the loan yet. An Opbouw loan opens only when the planning permission is final, the land has been valued as a plot and the documents are ready. Open projects are listed in the offering.
What happens if the project takes longer than planned?
The term of twelve to eighteen months is fixed for each project in the loan agreement, and your interest continues for as long as the loan runs. What happens if a project overruns that term is set out in the project's loan agreement and Information Memorandum.
What happens if the borrower does not meet its obligations?
First, the remedy period in the loan agreement applies. After that, the loan becomes due for all lenders in the project at once, and the foundation acts on behalf of the whole group. You do not have to go to the notary or the court yourself. The page on security explains how this works.